Why the Advertised Rate on a Bonus Saver Account Isn't What Most Savers Actually Earn
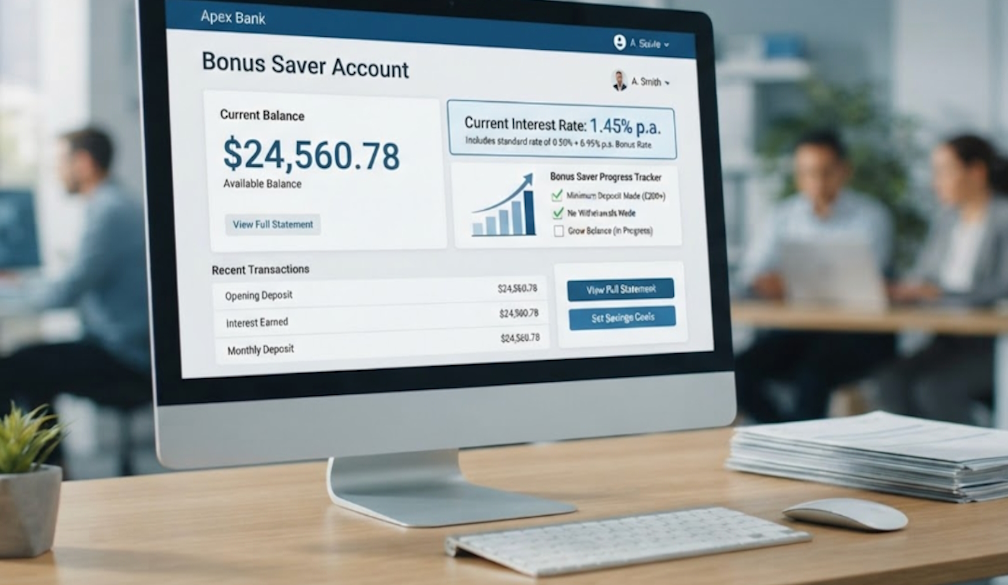
The interest rate advertised on a bonus saver account is the rate a customer earns only if every condition attached to it is met, in full, in every single month. For a meaningful share of savers, that turns out to be harder to sustain in practice than the headline number suggests, and the gap between the advertised rate and the rate actually received is rarely explained clearly at the point of opening the account.
How the Bonus Structure Actually Works
Most accounts in this category run on two tiers. A low base rate applies unconditionally to whatever balance sits in the account, regardless of activity. A significantly higher bonus rate is layered on top, but only for months where specific conditions are satisfied, typically a minimum deposit from an external source, no withdrawals during the month, and the account remaining open for the full period. The structure behind a bonus saver account generally rewards consistent saving behaviour over time rather than a lump sum left untouched, which is a different proposition to a standard savings account where the advertised rate simply applies to the balance.
Why One Withdrawal Can Cost an Entire Month, Not Just a Portion of It
This is the detail that catches people out most often. The bonus condition is typically all-or-nothing for the month, not proportional to the transaction. Withdrawing a small amount early in the month to cover an unexpected expense doesn't mean losing the bonus rate on just that portion, it usually means the entire balance reverts to the base rate for the whole month, even if the withdrawal was a fraction of the total held. Someone managing a large balance who dips into it once for a genuine emergency can lose considerably more in forfeited interest than the amount they withdrew, simply because the rule resets on a monthly cycle rather than tracking each dollar separately.
Why the Comparison Between Accounts Isn't Just About the Headline Number
Two bonus saver accounts advertising similar top rates can suit very different savers depending on how realistic the underlying conditions are for that person. Someone who deposits a fixed amount from their pay each month and rarely touches savings will likely capture the bonus rate consistently. Someone who occasionally needs to dip into savings for genuine short-term needs may find the base rate applies more often than the advertised rate suggests, regardless of which provider they choose. The more useful comparison isn't which account has the highest number attached to it, it's which set of conditions actually matches how that person saves.
What's Worth Checking Before Choosing One
A few details are worth confirming before assuming the advertised rate will apply consistently: whether the minimum monthly deposit needs to come from an external source or whether transfers between someone's own accounts count, exactly what counts as a withdrawal (some accounts treat linked card purchases differently to manual transfers), whether missing the condition in one month affects anything beyond that month's rate, and what maximum balance the bonus rate actually applies to, since amounts above that threshold typically earn the base rate regardless of activity.
How Interest Actually Accrues Versus When It's Paid
There's a separate detail worth understanding alongside the bonus conditions themselves: interest on these accounts is typically calculated daily but credited only once, usually on the last calendar day of the month. That distinction matters because a saver checking their balance mid-month won't see the interest reflected yet, even though it's accruing in the background based on that day's balance and whether the bonus conditions have held up so far. It also means the timing of a deposit within the month can matter for someone trying to maximise the bonus, since a deposit made on the last day still needs to satisfy the minimum external deposit requirement for that same month, not the next one.
Reading the Fine Print Isn't Optional Here
None of this makes bonus saver accounts a poor product, for a saver whose habits match the conditions, the structure can genuinely reward consistency in a way a flat-rate account doesn't. The point is that the advertised rate is a ceiling rather than a guarantee, and the target market determination and conditions of use documents that accompany any account like this spell out exactly what triggers the bonus and what forfeits it. Reading those before opening an account is a more reliable way to estimate actual returns than comparing headline percentages between providers.